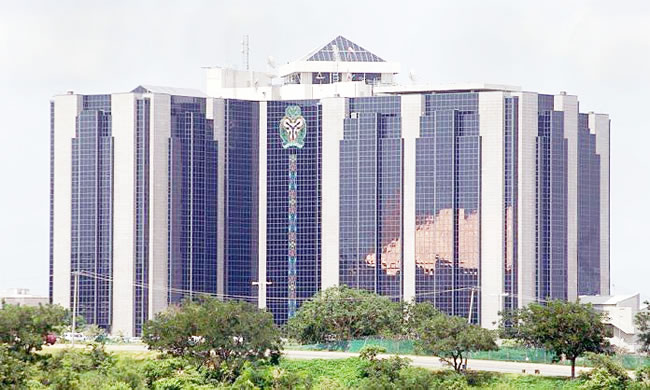
Abuja – The Central Bank of Nigeria (CBN) has issued new regulations governing the operations of non-security virtual assets in Nigeria, establishing a framework for the licensing, regulation and supervision of stablecoins, Deposit Money Tokens and Virtual Asset Service Providers (VASPs).
The regulations are aimed at promoting responsible innovation in digital payments and financial services while safeguarding monetary and financial stability, protecting consumers and addressing risks associated with money laundering, terrorism financing and other illicit financial activities.
Under the framework, stablecoins will be classified into two categories: Class 1, covering Naira-referenced stablecoins, and Class 2, covering foreign-currency-referenced stablecoins. The regulations also recognise Deposit Money Tokens issued by deposit money banks as digital representations of existing Naira deposit liabilities.
The CBN states that all persons and entities carrying out regulated virtual asset activities in or from Nigeria, or offering such services to Nigerians, must obtain the appropriate licence or authorisation. The requirement also applies to foreign issuers whose tokens are made available to Nigerian users, regardless of whether they maintain a physical presence in the country.
The regulations provide for six licensing and authorisation categories, including Naira-Referenced Issuer Licence (Class 1), Foreign Currency Issuer Licence (Class 2), Other Services Licence, Other Services Authorisation, Approval to Extend Permitted Activities and Deposit Money Token Licence.
Stablecoin issuers are required to establish Nigerian-incorporated entities, maintain a staffed physical office in the country and demonstrate effective local management and regulatory oversight. They must also disclose their ownership structures, directors, significant shareholders, sources of funds and proposed business operations.
The CBN further requires prospective issuers to obtain an Approval-in-Principle (AIP) before proceeding to final licensing. However, the preliminary approval does not permit them to commence operations or undertake regulated activities until all applicable conditions have been fulfilled and the final licence and token approval granted.
The regulations also establish strict reserve requirements to ensure that stablecoins are adequately backed by assets. Class 1 issuers are required to maintain a reserve deposit with the CBN, ordinarily representing 20 per cent of their reserve pool, alongside an additional minimum of 40 per cent in cash and high-quality liquid assets.
For Class 2 stablecoins, the reserve pool must be maintained in the currency to which the token is referenced, using approved cash deposits, sovereign securities and other eligible assets. Issuers must also maintain separate operational liquidity to meet expected and stressed redemption obligations in Nigeria.
The CBN further requires stablecoin issuers to provide holders with an enforceable right to redeem their tokens at their full value. Redemption requests must be processed within a maximum of one business day, while standard redemption fees and the payment of interest or yield to stablecoin holders are prohibited.
The regulations also prohibit the issuance, distribution and trading of algorithmic stablecoins that rely primarily on adjustments in supply and demand rather than adequate reserve backing. Tokens backed mainly by other virtual assets, those issued by sanctioned persons and stablecoins without enforceable redemption rights are also prohibited.
In addition, the CBN has placed restrictions on the promotion and advertisement of virtual asset products. Providers are prohibited from advertising regulated activities without the necessary approval, misrepresenting their licensing status or presenting stablecoins as conventional bank deposits or products covered by the Nigeria Deposit Insurance Corporation (NDIC).
The framework also strengthens consumer protection by requiring virtual asset service providers to disclose transaction charges, conversion rates, redemption procedures and associated risks. Providers must establish accessible channels for handling complaints, unauthorised transfers, fraud and transaction errors, while complying with Nigeria’s data protection requirements.
On anti-money laundering and counter-terrorism financing, the regulations require service providers to implement customer due diligence, identity verification, sanctions screening and transaction monitoring measures. They must also comply with the Financial Action Task Force’s Travel Rule, which requires relevant information about transaction originators and beneficiaries to accompany qualifying virtual asset transfers.
The CBN will also exercise supervisory oversight over regulated entities through periodic reporting, independent audits, reserve attestations and operational assessments. The Bank may inspect service providers, request transaction records and require modifications, suspension or discontinuation of activities considered inconsistent with the regulations or capable of posing risks to customers and the financial system.
The regulations provide for administrative and monetary sanctions for violations, including a minimum fine of ₦100 million for conducting regulated virtual asset activities without the required licence or operating outside an approved licence’s scope. An additional minimum fine of ₦1 million may also be imposed for every day the violation continues.
Other penalties include fines ranging from ₦50 million to ₦250 million for material breaches of reserve, capital or liquidity requirements, while violations involving reserve leverage or encumbrance attract fines of between ₦250 million and ₦500 million. Breaches of anti-money laundering requirements also attract a minimum fine of ₦50 million per violation.
The regulations further stipulate that fraudulent or deliberate misrepresentation to the CBN or the public concerning reserve management and stablecoin operations attracts a minimum fine of ₦500 million, alongside possible referral for criminal prosecution under applicable laws.
The CBN said the framework is designed to support the safe integration of virtual assets into Nigeria’s digital payments and settlement infrastructure while preserving the effectiveness of monetary policy, strengthening financial stability and protecting consumers from risks associated with the evolving virtual asset ecosystem.

Abuja’s number one hit music and talk radio station. Broadcasting 24/7 on 99.9FM across the Federal Capital Territory and streaming live worldwide.
© KissFM 99.9 All rights reserved.